Credit report errors, disputed properly
Your credit report is wrong. Fixing it shouldn't cost $100 a month.
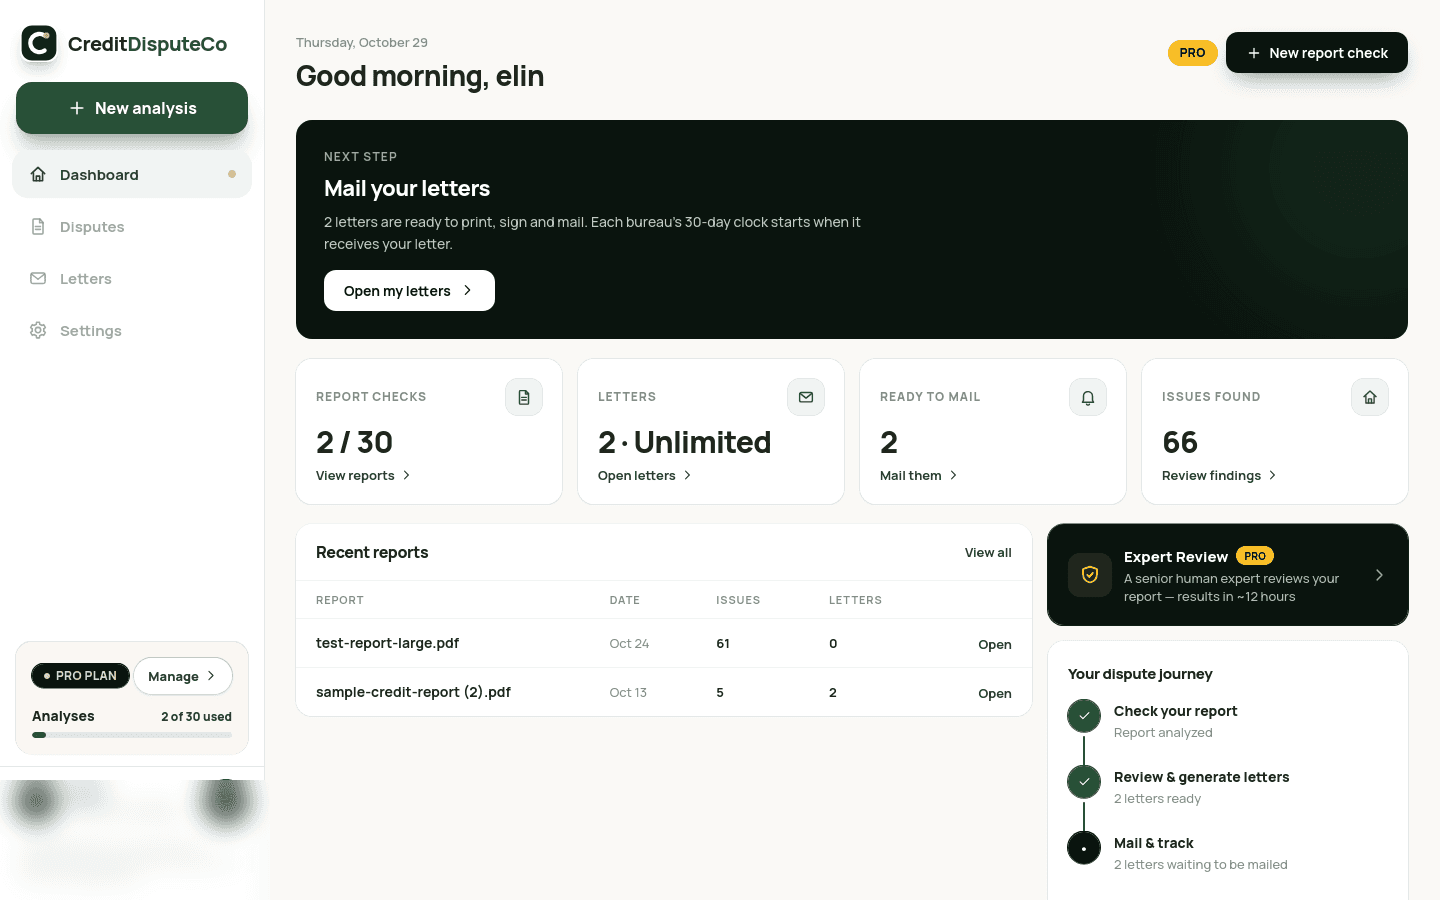
Upload your free report. CreditDisputeCo finds what's disputable, explains it in plain English, and writes the formal letters to all three bureaus. You approve every letter. You mail it. No retainer, no sales call.
Free to start · No card required · All 3 bureaus · Cancel anytime
3
bureaus covered — Experian, Equifax, TransUnion
30 days
bureau investigation deadline
15 days
Method-of-Verification response
4
letter types — bureau, creditor, identity theft, inquiry
Why this matters
A wrong report costs you in ways you don't see.
Lenders, landlords, and some employers check your report. One wrong late payment or one account that isn't yours can mean a higher rate, a denied rental, or a lost opportunity — and the error stays there until someone disputes it.
Main point: Errors don't fix themselves. Only a dispute starts the bureau's 30-day clock.
FCRA §611
Wrong late payments
You paid on time, but the report says late.
The report shows 30- or 60-day late payments, or the months aren't even printed. Lenders read this as risk — it can raise the rate you are offered or get an application denied.
FCRA §604
Inquiries you never authorized
A company pulled your report without permission.
A hard inquiry with no matching account. Each unauthorized inquiry is disputable on its own, and it does not belong on your file.
FCRA §605B / §611
Accounts that aren't yours
Someone else's debt, on your name.
A mixed file, or an account you closed years ago still listed as open. If it came from identity theft, the bureau must block it once you provide an identity theft report.
FCRA §605 / §623
Old or wrong balances
Paid, expired, or never updated.
A debt past its reporting limit, a paid account still shown unpaid, or a balance that never updated after you paid it down. The creditor that reported it can be asked to correct it directly.
How it works
Four steps. About five minutes. You stay in control.
Main point: You are in control at every step — nothing is disputed or sent without you saying so.
Upload your report
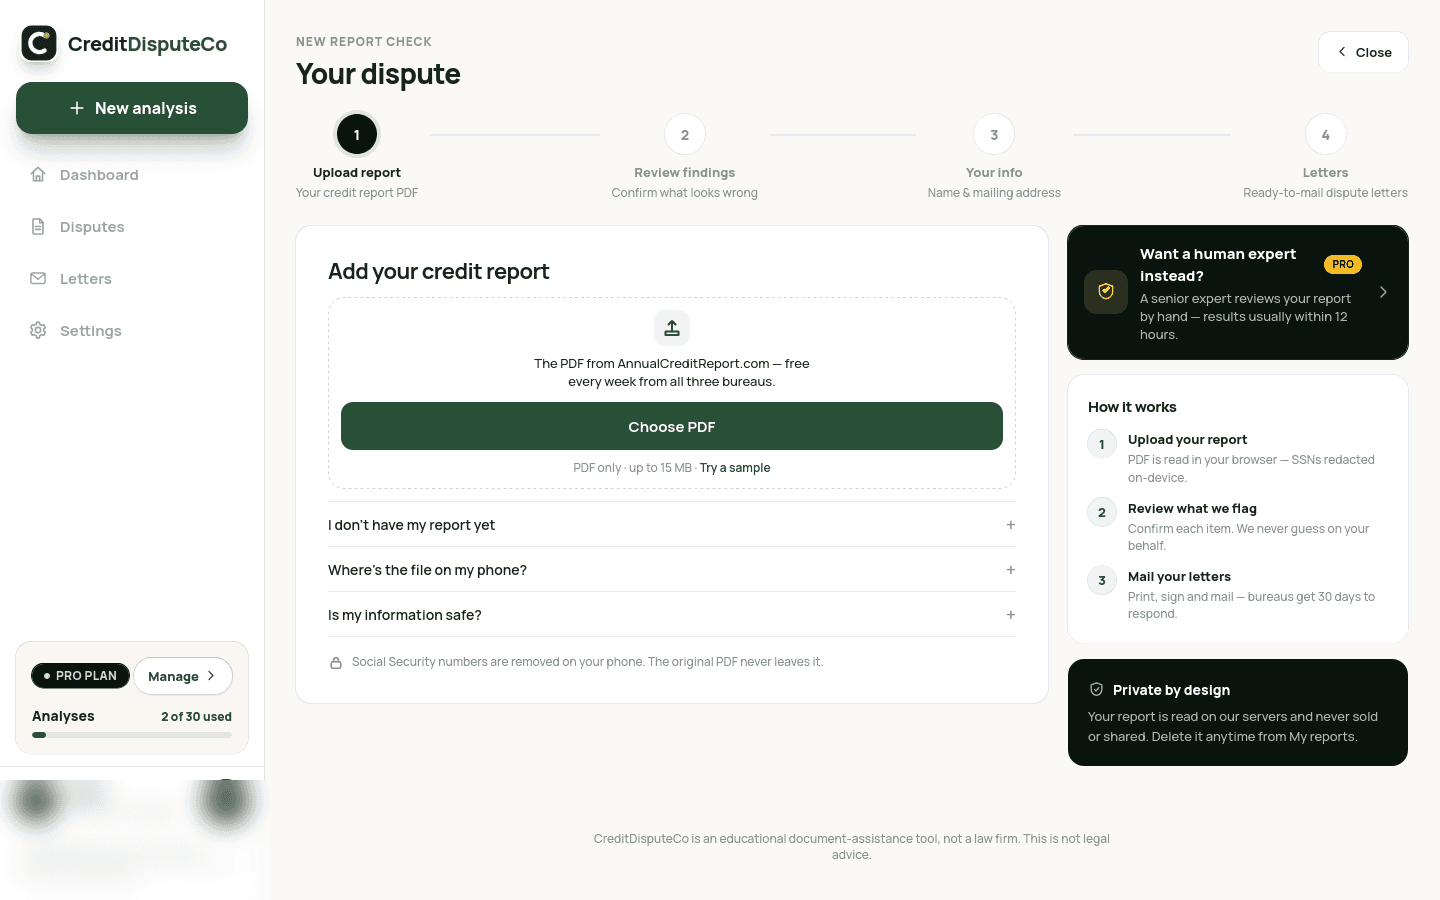
Your free PDF, nothing else needed.
Download it from AnnualCreditReport.com and upload it. Your Social Security number is removed on your device before anything is analyzed — the original PDF never leaves your device.
Review in plain English
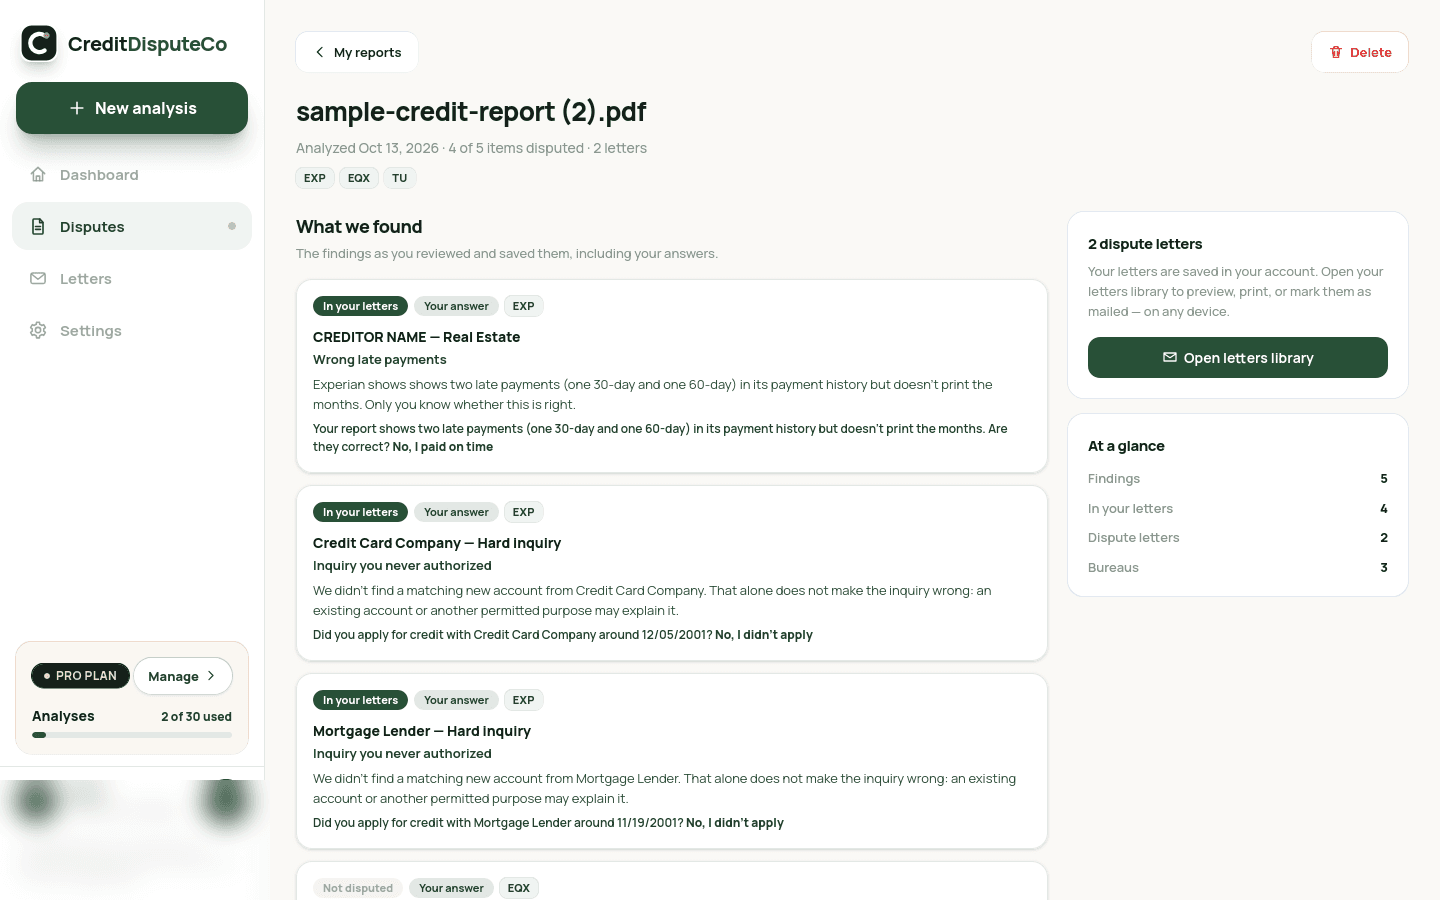
No bureau jargon. You decide what goes in.
Every finding is explained in plain words, with the FCRA section it falls under. You answer one question per item — only the items you confirm go into your letters.
Get letters ready to mail
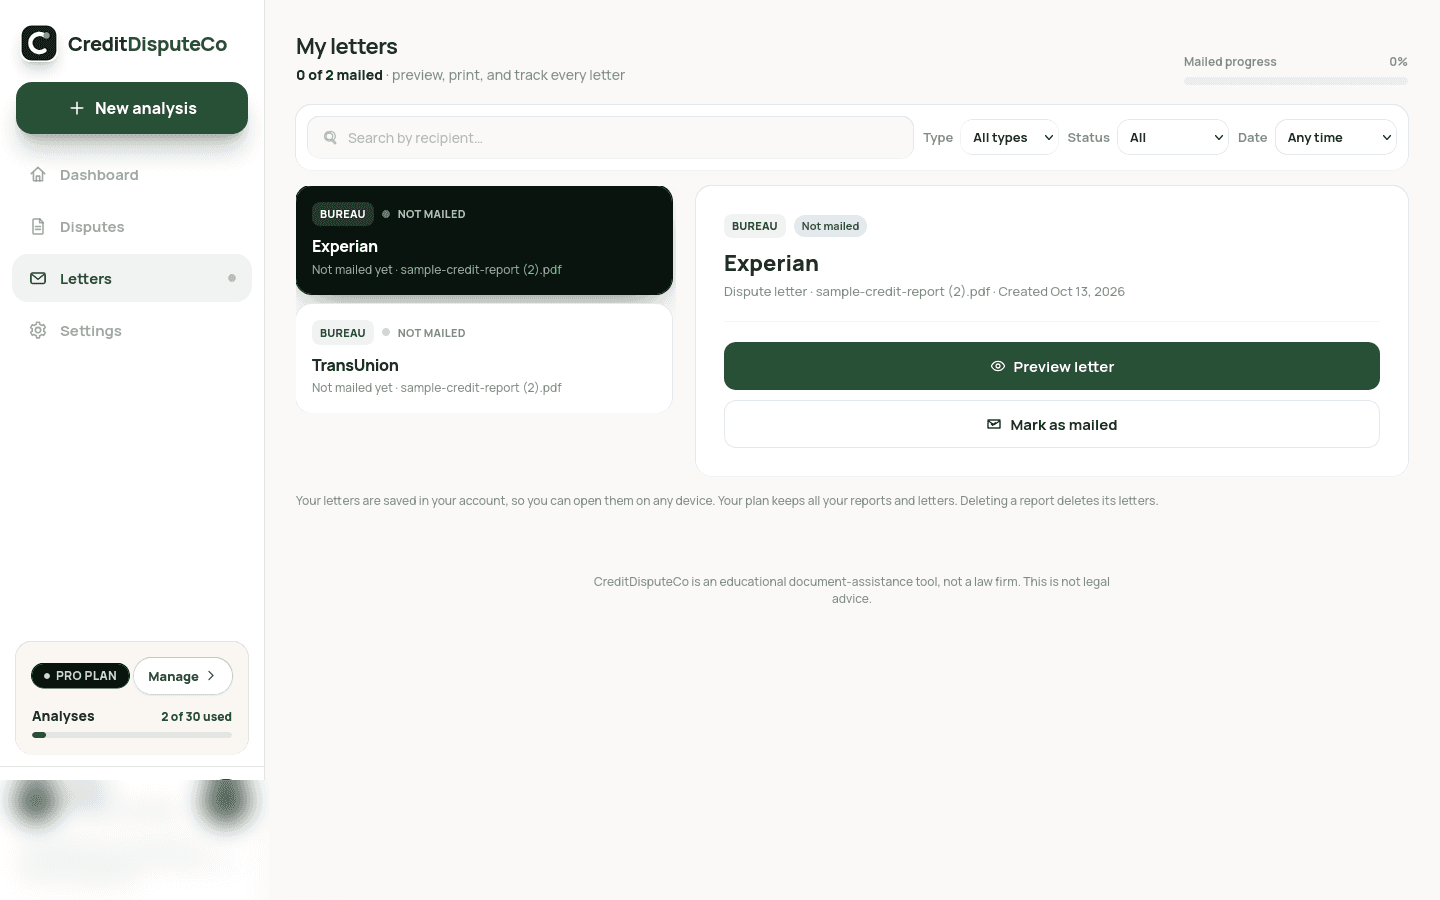
Formal letters, ready to print and sign.
Dispute letters for Experian, Equifax, and TransUnion, plus creditor letters on paid plans. Preview each one, print it, sign it, and mail it yourself. Nothing is sent without you.
Track the deadline
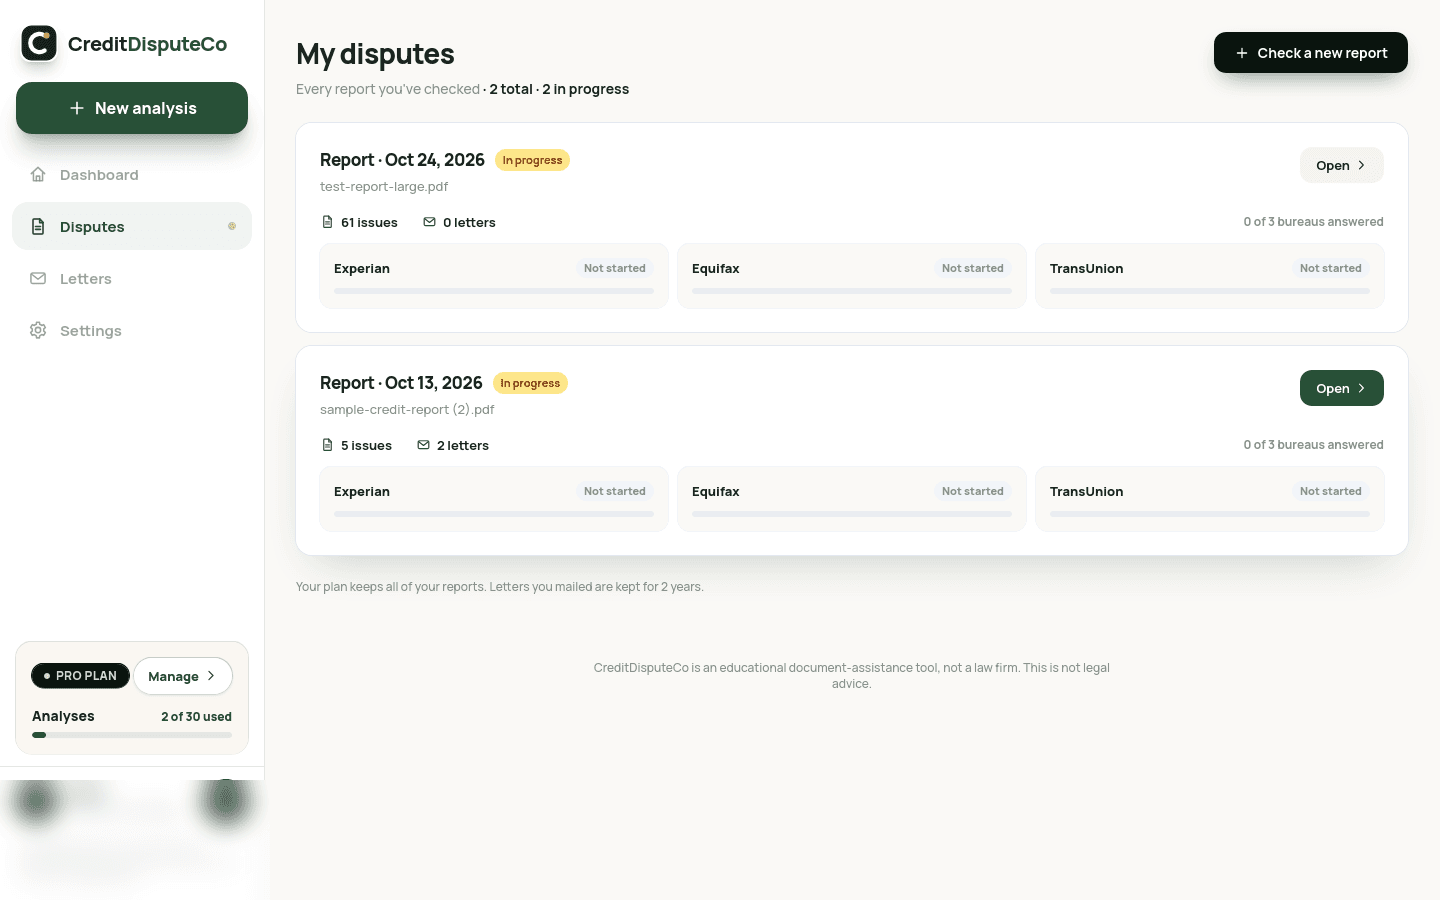
The clock, counted down for you.
Every report, every bureau, every answer in one list. The clock starts when the bureau receives your letter — not when you send it — and the tracker counts it down, including the 15-day Method-of-Verification clock.
The clock, day by day
What happens after you mail.
Disputing is a deadline game. Most people lose it because nobody tells them when the clock starts or what to do when the bureau answers.
Main point: The clock starts when the bureau receives your letter — not when you send it. Keep the mailing receipt.
You upload
Your report is analyzed and every finding is explained in plain English, with the law it falls under.
You mail your letters
Print, sign, and mail each letter yourself. Keep the mailing receipt — that is what starts the bureau's clock.
Bureau deadline
The bureau must finish its investigation within 30 days of receiving your dispute — 45 days in some cases, for example if you send more information mid-investigation.
Your next move
Ask how they verified it (Method-of-Verification, FCRA §611(a)(7) — answered within 15 days), dispute directly with the creditor, or file a free complaint with the CFPB.
What you get
Four letter types, not one template.
Main point: The right letter goes to the right party — a bureau letter does not fix a creditor's record.
Bureau disputes — FCRA §611
All plansUse this when: a bureau's file is wrong.
You tell Experian, Equifax, and TransUnion what is wrong, why, and what proof you have. The bureau must investigate and send you the result in writing.
Creditor (furnisher) disputes — FCRA §623
Plus and ProUse this when: the company that reported it is wrong.
Dispute directly with the bank, lender, or collector that furnished the item. Sometimes the furnisher corrects it faster than the bureau process.
Identity-theft blocks — FCRA §605B
All plansUse this when: the item came from identity theft.
The bureau must block it within 4 business days once you provide an identity theft report from IdentityTheft.gov (free) and proof of who you are.
Inquiry disputes — FCRA §604
All plansUse this when: someone pulled your report without permission.
Disputed with the company that pulled your report, not just the bureau — because the inquirer is the one who has to justify the pull.
Your SSN stays on your device
Removed before analysis.
The original PDF never leaves your device, and your report is never sold or shared.
You send everything
No letter goes out without you.
You print, sign, and mail it, so you always know exactly what was sent and when.
You can leave anytime
Cancel from Settings in one step.
Your letters and history stay in your account, even after you cancel.
Money-back guarantee
100% money-back guarantee if it doesn't work.
If CreditDisputeCo doesn't work for you, you get your money back. Start free, try it on your own report, and only pay when you need more than the free plan gives you.
Honest comparison
The famous names, side by side. One clear winner on value.
Same formal letters. Same federal law. The difference is who does the work, what you see, which bureaus are covered, and what you keep paying.
CreditDisputeCoBest value
You, guided
Free $0. Paid plans from $19/mo. No setup fee.
- Cost over 6 months
- $0 on Free, $114 on Plus, $294 on Pro.
- Who does the work
- You, guided, in about 5 minutes.
- You see every letter
- Yes. You preview and edit every letter before anything is mailed.
- Bureaus covered
- All three: Experian, Equifax, TransUnion.
- Your report and SSN
- Your SSN is removed on your device. The original PDF never leaves your device.
- Letter types
- Bureau, creditor, identity-theft, and inquiry letters.
- Outcome promises
- None — and that is honest. No one can guarantee deletions or score increases.
- Best for
- Disputing errors on all 3 bureaus, yourself, for $0–$49 a month.
Credit SaintDone-for-you firm
They do it for you
$79.99–$139.99/mo, plus a $99–$195 first-work fee.
- Cost over 6 months
- $579–$1,035 (first-work fee plus 6 months).
- Who does the work
- They dispute on your behalf, in monthly cycles.
- You see every letter
- Disputes are sent on your behalf.
- Bureaus covered
- All three.
- Your report and SSN
- You share your full report with the firm so it can work on it.
- Letter types
- Bureau challenges and creditor intervention letters.
- Outcome promises
- 90-day money-back if nothing is removed, with conditions.
- Best for
- Hands-off help, if you do not mind $80 or more a month.
Lexington LawDone-for-you firm
Law-firm service
$139.95/mo. No separate setup fee listed.
- Cost over 6 months
- $840 (6 months at $139.95).
- Who does the work
- Their team disputes on your behalf.
- You see every letter
- Disputes are sent on your behalf.
- Bureaus covered
- All three.
- Your report and SSN
- You share your full report with the firm so it can work on it.
- Letter types
- Bureau and creditor challenges.
- Outcome promises
- No guaranteed results — they say so themselves.
- Best for
- Hands-off legal help, at $139.95 a month.
Credit KarmaFree monitoring
Scores and alerts
Free $0. No card required.
- Cost over 6 months
- $0.
- Who does the work
- You, watching your own reports. It alerts you to changes.
- You see every letter
- No letters. TransUnion disputes are flagged in-app, not drafted.
- Bureaus covered
- TransUnion and Equifax only. No Experian.
- Your report and SSN
- You give it your personal details so it can pull your TransUnion and Equifax reports.
- Letter types
- None written for you.
- Outcome promises
- None — it is monitoring, not repair.
- Best for
- Free scores and monitoring — not for disputing.
Bottom line
Credit Karma is great — and free — for watching your scores, but it does not write dispute letters and it does not cover Experian. Done-for-you firms do the letters for you, at $80–$140 every month, and you rarely see them. CreditDisputeCo is the middle path: the same formal letters, visible and editable, for all three bureaus, from $0.
Competitor prices are public listings checked in October 2026 and change — confirm them on each firm's own site before you sign. CreditDisputeCo's prices are its own live prices: Free $0, Plus $19/mo, Pro $49/mo.
What's inside
Features built for clarity and control.
Everything you need to manage your dispute process, in one account.
AI issue flagging
Upload your report and get every potential issue translated into plain English — what it says, why it may be disputable, and the exact FCRA basis.
Editable findings
AI suggests — you decide. Review, edit, or remove every flagged item before any letter is generated. Nothing goes out you did not approve.
Bureau + furnisher letters
Formal §611 letters for Experian, Equifax, and TransUnion with verified mailing addresses — plus direct §623 disputes to the creditors themselves.
Round-two toolkit
If a bureau verifies anyway, generate a Method-of-Verification letter demanding they show their work — they must describe their procedure within 15 days.
30-day tracker
A personal timeline from mailing day to results day, saved in your account. Mark a letter as mailed and see exactly when the bureau's 30-day window (45 in some cases) opens and closes.
CFPB escalation guide
Still stuck? A guided path to the official Consumer Financial Protection Bureau complaint portal — free to file.
Expert human review
ProA senior expert goes through your report by hand — AI-assisted with careful manual passes — and publishes the findings for you. Results usually within 12 hours. Pro plan.
Pricing
Start free. Upgrade only if you need more.
Every plan includes dispute letters for all three bureaus. Paid plans add creditor letters, more analyses, and longer history.
Free
$0
1 dispute package / month
- 1 analysis (one-time)
- 3 letters (one-time)
- 30-day report history
- No credit card required
No credit card required
Plus
$19/mo
- 10 analyses / month
- Unlimited letters
- 12-month report history
- Creditor letters
- Email support
Card required — cancel anytime
Pro
$49/mo
- 30 analyses / month
- Unlimited letters
- Unlimited history
- Creditor letters
- Expert human review
- Priority support
Card required — cancel anytime
Prices in USD. Secure checkout via our payment provider — cancel anytime from Settings, and your letters and history stay in your account.
FAQ
Questions, answered honestly.
Do I need to know credit law to use this?
No. The app flags what looks wrong, explains it in plain English, and cites the FCRA section for you. You only confirm what is actually true about your own accounts.
Where do I get my credit report?
From AnnualCreditReport.com — the official site where you can get your free reports from Experian, Equifax, and TransUnion. Download the PDF and upload it here.
Do you send the letters for me?
No, and that is deliberate. You preview every letter, print it, sign it, and mail it yourself, so you always know exactly what was sent and when the bureau's clock started.
How long does a dispute take?
The bureau has 30 days from receiving your letter to investigate (45 in some cases). If it says an item is verified, you can ask for its verification method within 15 days, dispute with the creditor, or file a free CFPB complaint.
Is my Social Security number safe?
It is removed on your device before analysis, so the original PDF — with your SSN — never leaves your device. Your letters and history stay in your account.
Can I cancel anytime?
Yes, from Settings. Your letters and history stay in your account after you cancel, and paid plans are billed monthly or yearly — yearly is two months free.
Check your report. It takes five minutes.
Download your free report from AnnualCreditReport.com, upload it, and see what's actually wrong — before a lender does.
Create your free accountFree to start · No credit card required